Article-At-A-Glance:
- Delayed gratification is one of the most powerful financial habits you can build — and science backs it up with decades of research.
- The famous Marshmallow Experiment revealed that children who could wait for a reward went on to have better financial outcomes, healthier relationships, and higher academic achievement.
- Your brain is literally wired to prefer immediate rewards — understanding why makes it easier to fight back.
- Small sacrifices, compounded over time, create life-changing financial results that instant spending never can.
- Keep reading to discover the exact strategies that rewire your spending habits and make waiting feel like winning.
The ability to wait is worth more than most people realize — and the data proves it.
Every financial decision you make comes down to a simple trade-off: enjoy something now, or gain something greater later. Most people default to now. But the ones who consistently choose later? They tend to end up wealthier, less stressed, and more in control of their lives. Understanding the benefits of delayed gratification isn’t just an academic exercise — it’s a practical roadmap to building real financial security.
If you’re looking for a starting point, resources like practical saving guides can help bridge the gap between knowing you should save and actually doing it. The psychology behind why we spend impulsively is well-documented, and so are the strategies to overcome it.
Waiting Pays Off — Here’s the Proof
Delayed gratification isn’t a personality trait you either have or don’t. It’s a skill — one that can be developed, practiced, and strengthened over time. And the payoff for developing it is enormous.
Research consistently shows that individuals who demonstrate the ability to delay rewards tend to accumulate more savings, carry less debt, and make smarter long-term investments. This isn’t about being cheap or denying yourself enjoyment. It’s about understanding that timing changes the value of everything.
- People who save consistently are more likely to retire comfortably
- Delaying a purchase often reduces the desire for it entirely
- Waiting builds confidence in your ability to manage money
- Long-term thinkers report lower financial stress and higher life satisfaction
The connection between patience and prosperity isn’t coincidental. It’s causal.
The Marshmallow Experiment and What It Revealed
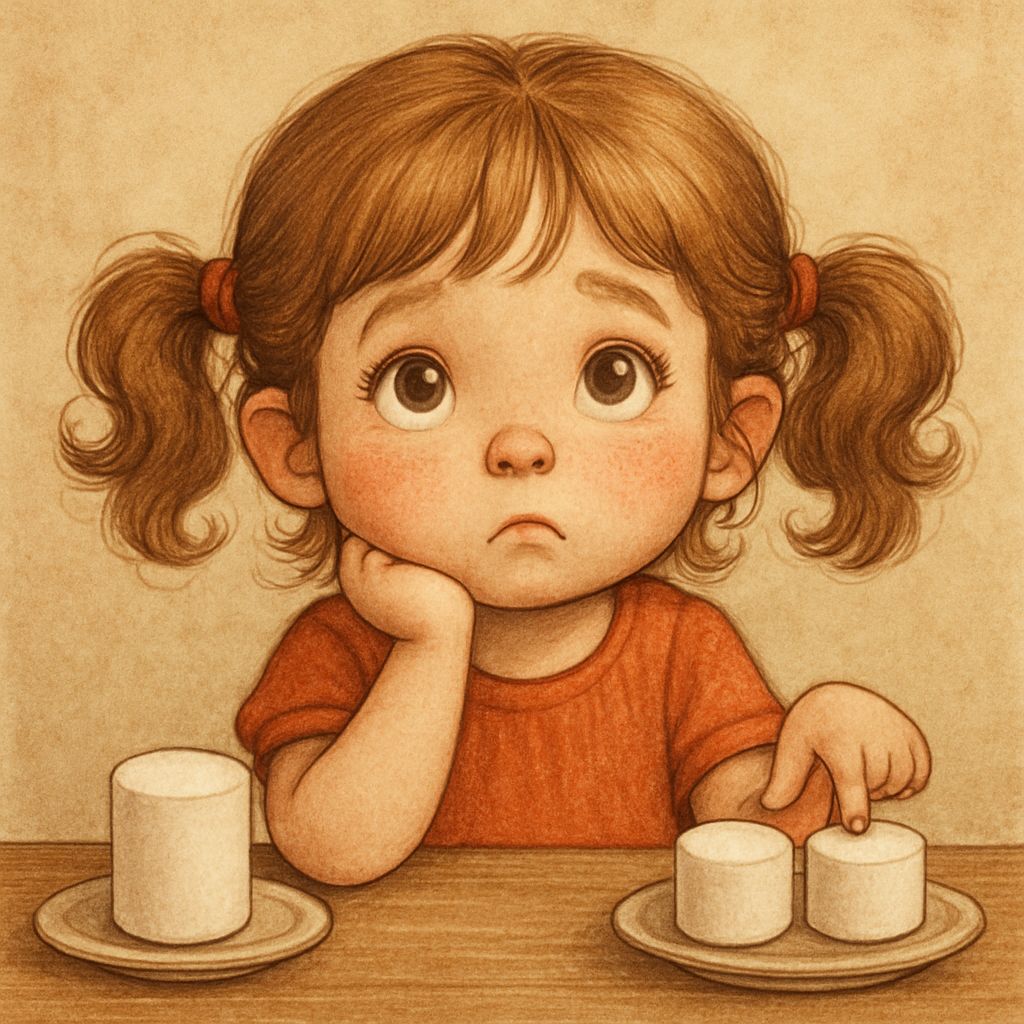
In the late 1960s, psychologist Walter Mischel conducted what became one of the most famous behavioral studies in history at Stanford University. Children were offered one marshmallow immediately, or two marshmallows if they could wait 15 minutes without eating the first one. Simple setup. Profound results.
The children who waited went on to demonstrate significantly better outcomes across multiple areas of life — higher SAT scores, better stress management, and stronger social skills. Follow-up studies tracked these same individuals into adulthood and found that the ability to delay gratification at age four was a reliable predictor of long-term success. What started as a marshmallow became a window into the mechanics of self-control.
Importantly, later research added important nuance. A 2018 study published in Psychological Science by Tyler Watts, Greg Duncan, and Haonan Quan found that a child’s ability to wait was also influenced by their environment and socioeconomic background — meaning trust in the system matters. If a child didn’t believe the second marshmallow was actually coming, waiting wasn’t irrational. It was smart. The same logic applies to adult financial decisions.
Why Instant Gratification Costs You More Than You Think
Every time you choose instant gratification, there’s a hidden cost that rarely shows up on the receipt. That $6 coffee every morning isn’t just $6 — it’s $2,190 a year that never makes it to your savings account. That impulse purchase on a credit card isn’t just the sticker price — it’s that price plus interest, plus the opportunity cost of what that money could have grown into.
Instant gratification is expensive because it trades long-term value for short-term comfort. And it compounds in the wrong direction. The more you give in to immediate impulses, the more normal it feels — which makes it progressively harder to choose the better option. The habit builds either way. The question is which habit you’re building.
What Delayed Gratification Actually Means for Your Money
Applied to personal finance, delayed gratification is the practice of making conscious, forward-thinking choices with your money instead of reactive, emotion-driven ones. It means buying the used car instead of the new one, cooking at home instead of eating out five nights a week, and letting your savings account grow instead of draining it for wants disguised as needs.
This isn’t about deprivation. It’s about intention. When you delay a purchase, you’re not saying “I can never have this.” You’re saying “I’ll have this when I’ve earned it without compromising my future.” That shift in mindset is the foundation every solid financial plan is built on, as it aligns with the psychology behind choices.
The Difference Between Wants and Needs
The line between wants and needs gets blurry fast — especially when you’ve convinced yourself that the newest phone model is a necessity. A need is something that sustains your health, safety, and basic functioning. A want is everything else. Delayed gratification starts with being honest about which category your spending falls into, and having the discipline to treat them differently.
How Waiting Changes the Way You Value Money
Something interesting happens when you practice waiting before spending: your perception of value shifts. That item you were desperate to buy two weeks ago? Often, you don’t even want it anymore. Studies on consumer behavior show that the emotional urgency driving most impulse purchases fades significantly within 48 to 72 hours. Waiting doesn’t just save money — it filters out purchases that were never worth making in the first place.
Over time, this rewires how you relate to money. You start seeing it less as something to spend and more as something to deploy strategically — a tool that works harder the longer you hold onto it.
The Compounding Effect of Small Sacrifices
Compound interest is the financial world’s most powerful force, and delayed gratification is the behavior that unlocks it. Saving $200 a month starting at age 25 versus starting at 35 doesn’t result in a slightly better outcome — it results in a dramatically different retirement. The math is unambiguous: time in the market, funded by consistent saving habits, creates wealth that no single windfall can replicate.
The Science Behind Why Waiting Is Hard
If delayed gratification were easy, everyone would do it. The reason most people struggle isn’t a lack of willpower — it’s biology. The human brain is not naturally optimized for long-term thinking. It evolved to prioritize immediate survival, which means it’s running software that’s thousands of years out of date when it comes to modern financial decisions.
Understanding the neuroscience behind impulsive spending doesn’t excuse it, but it does explain it — and explanation is the first step toward change.
How Your Brain Fights Against Future Rewards
When you anticipate an immediate reward, your brain releases dopamine — the same chemical involved in pleasure, motivation, and addiction. This dopamine hit makes the immediate option feel disproportionately attractive compared to a future reward, even when the future reward is objectively larger. Brain imaging studies show that the limbic system, which governs emotion and immediate desire, activates strongly for near-term rewards, while the prefrontal cortex — responsible for rational planning — has to work harder to compete. To learn more about how dopamine affects your brain, read this article on what dopamine actually does.
The result is an internal tug-of-war every time you face a financial decision. Your emotional brain wants the thing now. Your rational brain knows better. And without deliberate strategies in place, the emotional brain wins more often than it should.
This is why willpower alone is a losing strategy. Relying purely on self-control to resist spending is like trying to outrun a car. The game changes when you build systems — automatic savings transfers, cooling-off periods, goal visualization — that remove the moment of temptation entirely.
- Dopamine release makes immediate rewards feel more valuable than they are
- The limbic system responds faster and stronger to present pleasures than future ones
- Decision fatigue weakens your resistance to impulse spending as the day progresses
- Emotional spending is triggered by stress, boredom, and social pressure — not genuine need
- Environmental cues — like notifications, sales alerts, and store layouts — are engineered to exploit these weaknesses
Present Bias: Why Today Always Feels More Important
Present bias is the tendency to overweight immediate rewards relative to future ones — even when you logically know the future reward is better. It’s why you set a budget on Monday and abandon it by Friday. It’s why retirement feels abstract and the new sneakers feel urgent. The future version of you feels like a stranger, and your brain allocates resources accordingly.
The good news is that present bias can be countered once you recognize it. Techniques like mental time travel — vividly imagining your future self enjoying the result of your savings — have been shown to increase the likelihood of choosing delayed rewards. When your future self stops feeling hypothetical and starts feeling real, protecting their financial security becomes a priority worth acting on today. For more insights, you can explore the concept of delayed gratification.
Delayed Gratification Saving Strategies That Actually Work
Knowing you should delay gratification and actually doing it are two very different things. The strategies below aren’t motivational fluff — they’re behavioral tools backed by psychology and real-world results. Each one is designed to reduce the friction of saving and increase the friction of impulsive spending.
The most important thing to understand before diving in is that no single strategy works in isolation. The people who build lasting saving habits combine multiple approaches and layer them together until the system runs almost automatically. Think of each strategy as a gear — individually useful, but most powerful when working in sync with the others.
Start by picking two or three that match your biggest spending triggers. Master those first. Then add more. The goal isn’t perfection on day one — it’s building a framework that makes delayed gratification the path of least resistance rather than the path of most effort.
Here’s a snapshot of how each strategy targets a specific financial weakness:
Strategy
Weakness It Targets
Time to See Results
30-Day Rule
Impulse purchasing
Immediate
Savings Goal + Deadline
Vague financial intentions
1–3 months
Automated Savings
Spending before saving
First pay cycle
Visual Progress Tracker
Motivation drop-off
2–4 weeks
Staged Rewards
All-or-nothing thinking
Ongoing
1. The 30-Day Rule for Impulse Purchases
The 30-Day Rule is straightforward: when you feel the urge to buy something that isn’t a planned necessity, write it down and wait 30 days before purchasing it. If you still want it after a month, buy it guilt-free. If the urge has faded — which it usually does — you’ve just saved yourself money you would have regretted spending.
- Keep a running “want list” in your phone’s notes app or a dedicated notebook
- Record the item, the price, and the date you first wanted it
- Revisit the list at the end of each month and evaluate each item honestly
- If the desire is still strong and it fits your budget, allow the purchase intentionally
- If the urge is gone, cross it off and note how much you saved
That last step matters more than it seems. Tracking your “saved from impulse” total creates a visible record of your self-control paying off — which reinforces the behavior and makes it easier to repeat. Over a year, most people are shocked by how much this single habit saves them.
The 30-Day Rule works because it inserts time between emotion and action. That gap is where rational thinking lives. It doesn’t eliminate wanting things — it just gives your prefrontal cortex a chance to weigh in before your wallet opens.
2. Set a Savings Goal With a Specific Deadline
Vague goals are where saving habits go to die. “I want to save more money” is not a plan — it’s a wish. A real savings goal looks like this: “I will save $3,000 for an emergency fund by December 31st by setting aside $250 per month.” The specificity of what, how much, and by when transforms an intention into an actionable target. Research on goal-setting consistently shows that specific, time-bound goals produce dramatically better outcomes than open-ended ones. When you know exactly what you’re waiting for and when you’ll get there, the wait becomes purposeful instead of painful.
3. Automate Your Savings Before You Can Spend It
Automation is the single most effective saving strategy for people who struggle with impulse spending — because it removes the decision entirely. Set up an automatic transfer from your checking account to a dedicated savings account the same day your paycheck lands. You never see the money sitting in your account, so you never have the opportunity to rationalize spending it. Most banks and credit unions offer this feature at no cost, and apps like Digit, Qapital, and Chime have built entire platforms around automating micro-savings in ways that feel nearly invisible until you check your balance and realize how much you’ve accumulated.
4. Use a Visual Progress Tracker to Stay Motivated
Motivation fades fast when the goal feels abstract. A visual savings tracker makes your progress tangible — and tangible progress is addictive in the best possible way. Whether it’s a printed savings chart on your fridge, a thermometer graphic you color in by hand, or a digital dashboard inside a budgeting app, seeing the gap between where you are and where you want to be creates accountability and momentum simultaneously. Understanding how attachment styles influence financial decisions can also provide insight into your saving habits.
- Printed trackers: Simple, free, and visible every day — great for physical reminders
- Budgeting apps: Mint, YNAB (You Need A Budget), and Personal Capital all offer goal-tracking features with visual dashboards
- Spreadsheets: A custom Google Sheets tracker gives you full control over milestones and categories
- Vision boards: Pairing your savings tracker with an image of your goal — a house, a vacation, an emergency fund thermometer — strengthens emotional connection to the outcome
The psychology behind this is called the “goal gradient effect” — the closer you get to a goal, the more motivated you become to reach it. Visual trackers make that proximity obvious, which accelerates the final push toward your target.
Update your tracker weekly, not monthly. The more frequently you engage with your progress, the more your savings habit becomes part of your identity rather than just a temporary effort.
5. Reward Yourself in Stages, Not All at Once
Delayed gratification doesn’t mean zero gratification. One of the biggest mistakes people make when trying to save is treating every milestone as invisible until the final goal is reached. That’s a recipe for burnout. Instead, build in deliberate micro-rewards along the way — small, affordable celebrations that acknowledge real progress without derailing the larger plan.
For example, if you’re saving $6,000 for a down payment, reward yourself at $1,500, $3,000, and $4,500 with something meaningful but inexpensive — a nice dinner out, a movie night, a weekend day trip. These staged rewards serve as proof that the system is working, which makes it far easier to stay committed through the longer stretches where progress feels slow. The goal isn’t to deprive yourself — it’s to match the size of your reward to the scale of your progress.
How to Build the Delayed Gratification Habit
Strategies are only useful if you actually use them — and that requires building a habit structure that makes delayed gratification your default mode, not a constant uphill battle. Habit formation follows a predictable pattern: cue, routine, reward. The trick is engineering each of those three elements to support saving instead of spending.
Start Small and Scale Up
The biggest mistake new savers make is trying to overhaul everything at once. They cut every expense, set an aggressive savings target, and white-knuckle their way through the first two weeks — only to give up entirely when the plan feels unsustainable. The far more effective approach is to start with one tiny change and prove to yourself that you can stick to it.
Save $25 a week before you try to save $500 a month. Use the 30-Day Rule on small purchases before applying it to big ones. Build trust with yourself by keeping small promises first. Your brain registers each kept commitment as evidence that you are someone who follows through — and that self-image becomes the engine that powers every bigger financial decision that follows.
Replace Spending Triggers With Saving Triggers
Every impulse purchase has a trigger — boredom, stress, social media scrolling, a bad day at work. These triggers don’t disappear just because you decide to save more money. What you can do is intercept them and redirect them toward a saving behavior instead of a spending one. This is called trigger replacement, and it’s one of the most durable habit strategies in behavioral psychology.
Map out your top three spending triggers and assign a saving action to each one. If stress sends you to online shopping, replace it with a five-minute check of your savings progress tracker instead. If boredom leads to browsing retail sites, replace it with transferring $10 to your savings account and updating your goal thermometer. The trigger stays the same — the response changes. Over time, the new response becomes just as automatic as the old one, except now it’s building your future instead of draining it.
Track Every Win, No Matter How Small
Win Type
Example
Why It Matters
Impulse Avoided
Skipped a $45 impulse buy
Reinforces self-control identity
Savings Milestone
Hit $500 in emergency fund
Activates goal gradient motivation
Habit Streak
30 days of no eating out
Builds consistency and confidence
Substitution Success
Cooked instead of ordering delivery
Proves the habit is working
Automated Save
Auto-transfer completed on payday
Confirms the system is running
Most people only notice their financial wins when they’re large and obvious — a fully funded emergency account, a paid-off credit card, a down payment finally reached. But the habit of saving is built in the small moments, not the big ones. Every time you resist an impulse purchase, every time your automated transfer goes through, every time you cook at home instead of ordering delivery — that’s a win worth acknowledging. Understanding the psychology behind choices can further enhance your ability to make smart financial decisions.
Keep a simple wins log. It doesn’t need to be elaborate — a note in your phone, a line in a journal, a sticker on a calendar. The act of recording a win creates a moment of positive reinforcement that signals to your brain: this behavior is worth repeating. That signal, repeated consistently, is how saving stops feeling like sacrifice and starts feeling like identity.
The compounding effect of tracking small wins is psychological, not just financial. Research on self-efficacy — your belief in your own ability to succeed — shows that perceived progress directly increases motivation and persistence. When you can look back and see a trail of small victories, the next right choice becomes easier to make. The evidence of your own consistency becomes your most powerful motivator.
Don’t wait for a big milestone to feel good about your progress. The person who saves $20 this week when they saved nothing last week has made a more meaningful change than someone who saves $500 once and then forgets about it for six months. Consistency beats intensity every time in personal finance. Celebrate accordingly and understand how attachment styles influence financial decisions.
The Long-Term Payoff Makes the Wait Worth It
Every uncomfortable moment of choosing to save instead of spend is an investment in a version of your life that is genuinely less stressful, more free, and more secure. Financial anxiety is one of the leading sources of stress for adults — and it doesn’t disappear with a higher income. It disappears with better habits. The people who practice delayed gratification consistently don’t just end up wealthier — they end up with options. The option to leave a job that drains them. The option to handle an emergency without panic. The option to retire on their terms. That kind of freedom isn’t bought with one good decision. It’s built with thousands of small ones, made over years, compounded into something extraordinary.
Frequently Asked Questions
Here are answers to the most common questions about delayed gratification and how it applies to building better saving habits.
What is delayed gratification in saving money?
Delayed gratification in saving money is the practice of choosing a larger future financial reward over a smaller immediate one. It means resisting the urge to spend money now in favor of saving it for a more meaningful goal later — whether that’s an emergency fund, a home down payment, retirement, or simply the security of knowing you have a financial cushion. It’s not about never enjoying your money. It’s about being intentional with when and how you enjoy it.
How long should you wait before making a purchase?
For most non-essential purchases, a 30-day waiting period is the gold standard. For smaller impulse items under $50, even a 48 to 72-hour pause is enough to let the emotional urgency fade and allow a rational evaluation to take its place. The bigger the purchase, the longer the waiting period should be. A major purchase — furniture, electronics, a vehicle — warrants at least 30 days of deliberate consideration, comparison shopping, and budget review before committing.
Can delayed gratification really improve financial outcomes?
Yes — and the evidence is substantial. Decades of behavioral research, beginning with Mischel’s Stanford Marshmallow Experiment and followed by numerous longitudinal studies, consistently show that individuals who demonstrate stronger delayed gratification tendencies accumulate more savings, carry less consumer debt, and make more consistent long-term investment contributions than those who prioritize immediate rewards.
The mechanism is straightforward: every dollar not spent impulsively is a dollar available to save, invest, or deploy strategically. Over years and decades, that difference compounds dramatically. A person who saves $300 per month starting at age 25 versus age 35 doesn’t just have 10 more years of savings — they have potentially hundreds of thousands of dollars more in retirement wealth, depending on investment returns. Delayed gratification is the behavior that makes that difference possible.
What is the best savings strategy for someone who struggles with impulse spending?
Automation is the single best starting point for chronic impulse spenders. Set up an automatic transfer to a separate savings account the moment your paycheck hits — ideally to an account at a different bank that takes two to three business days to access. This creates both a physical and psychological barrier between your spending money and your savings. From there, layer in the 30-Day Rule for non-essential purchases and a visual savings tracker to maintain motivation. The combination of reducing access, delaying decisions, and making progress visible addresses the three core drivers of impulse spending simultaneously.
How do you stay motivated when saving for a long-term goal?
Long-term saving motivation collapses when the goal feels distant and abstract. The solution is to make it feel immediate and concrete at every stage of the journey. Several proven techniques help with this consistently, such as understanding attachment styles and their influence on financial decisions.
- Visualize your future self enjoying the outcome of your savings — research shows this increases willingness to delay rewards significantly
- Break the goal into monthly milestones so there’s always a near-term target within reach
- Celebrate each milestone with a small, intentional reward that acknowledges progress without derailing the plan
- Use a visual tracker updated weekly to make incremental progress visible and satisfying
- Share your goal with someone who will hold you accountable — social commitment dramatically increases follow-through
- Revisit your “why” regularly — the deeper reason behind your goal (security, freedom, family) keeps motivation rooted in meaning rather than willpower
One of the most effective long-term motivation tools is something called “temptation bundling” — pairing the act of reviewing your savings progress with something you genuinely enjoy, like a favorite podcast, a good coffee, or a relaxing Sunday morning ritual. By associating your savings habit with a pleasurable experience, you create a positive feedback loop that makes showing up for the habit feel rewarding in itself.
It also helps to remember that motivation is not a constant state — it fluctuates. The goal isn’t to stay motivated every single day. The goal is to build a system that keeps saving happening even on the days when motivation is nowhere to be found. Automation, accountability, and environmental design are what carry you through those gaps. Motivation gets you started. Systems keep you going.
If you ever feel your momentum slipping, go back to basics: revisit your goal, update your tracker, make one small saving action right now, and remind yourself that every person who has ever reached a significant financial milestone felt exactly the same doubt you’re feeling — and kept going anyway. The wait is always worth it when you know what you’re waiting for.